Tabby vs Tamara (2026): Which Buy Now, Pay Later App Is Better for Gulf Expats?
Both split your purchase into four interest-free payments — but they differ on late fees, longer plans, cards and subscriptions. A side-by-side comparison for Gulf expats, and who wins each round.
By the Finance Arabia editorial team7 min read
Tabby and Tamara are the two biggest buy now, pay later (BNPL) apps in the Gulf, and you'll see at least one of them at nearly every online checkout in the UAE, Saudi Arabia and Kuwait. They look almost the same: split your purchase into four payments with no interest. Look closer, though, and they differ on late fees, longer plans, cards, subscriptions and where they operate. For expats there's an extra issue: since July 2026 both appear on UAE credit reports. This comparison sets them side by side so you can pick the one that fits how you spend.
Quick answer
- Choose Tabby if you want an all-in-one money app: the Tabby Card, Tabby Cash for transfers in the UAE, more payment options and the widest store network.
- Choose Tamara if you want the simplest split-in-4 with no late fees, or you live in Bahrain, where Tamara holds a central bank licence.
- Using both? That's fine, as long as you track the total you owe across the two apps. Banks now see both.
At a glance
| Tabby | Tamara | |
|---|---|---|
| Founded | 2019, Dubai (HQ in Riyadh since 2023) | 2020, Riyadh |
| Countries | Saudi Arabia, UAE, Kuwait | Saudi Arabia, UAE, Kuwait, Bahrain |
| Saudi licences | SAMA consumer and SME finance licences; owns the Tweeq wallet | SAMA consumer finance and BNPL licence (March 2025) |
| Other licences | Stored Value Facilities licence in the UAE (Tabby Cash) | First BNPL licence from the Central Bank of Bahrain |
| Latest valuation | $6.5bn (Series F, September 2026) | $1bn+ (December 2023) |
| Split in 4 | Yes, no interest when paid on time | Yes, no interest |
| Longer plans | Up to 12 monthly payments for eligible users (profit margin applies) | Longer plans at selected Saudi merchants (fees may apply) |
| Late fees | None on split-in-4 in Saudi Arabia; collection charges in the UAE | No late fees, according to Tamara |
| Card | Tabby Card (Visa): split in 4 almost anywhere | Shop-anywhere features through Smart subscriptions |
| Paid subscription | Tabby+: AED 49/month after a free first month | Tamara Smart and Smart+ (price shown in app) |
| UAE credit report | Yes, since July 2026 | Yes, since July 2026 |
1. Split in 4: practically a tie
The core product is the same in both apps. You pay a quarter at checkout and the rest in three monthly payments, charged automatically to your card. Neither charges interest when you pay on time, and both make their money mainly from merchant commissions, not from you.
A small number of stores may add a service fee in either app. It appears before you confirm, so always check the total.
Winner: tie.
2. Late payments: Tamara is more forgiving
This is the clearest difference between them, especially in the UAE:
| If you miss a payment | Tabby | Tamara |
|---|---|---|
| Late fee | No late fees on split-in-4 in Saudi Arabia (since December 2023). In the UAE, collection charges apply to missed payments. | No late fees |
| New purchases | Blocked until you catch up | May be blocked until you catch up |
| Credit record | Late payments can hurt your credit score | Late payments can hurt your credit score |
"No late fees" doesn't mean no consequences. In both apps a missed payment can block new purchases and damage your credit record, and that matters most in the UAE now that both report to the credit bureau.
Winner: Tamara.
3. Bigger purchases and longer plans: Tabby offers more
For a laptop, furniture or a phone you may want more than four payments. Tabby goes further here: eligible users in Saudi Arabia can spread purchases up to SAR 50,000 over as many as 12 monthly payments, under a Sharia-compliant murabaha structure with a profit margin. Tamara also offers longer plans at selected Saudi merchants, and processing fees may apply.
Longer plans in either app are not free. Compare the total you'll pay with the cash price before you pick one.
Winner: Tabby, for flexibility.
4. Cards, transfers and extras: Tabby is a wider money app
Tabby has been building a full financial app on top of BNPL:
- Tabby Card: a Visa card that lets you split purchases in 4 almost anywhere, including stores that don't offer Tabby at checkout.
- Tabby Cash (UAE): an account for holding money, spending and transfers, under a Stored Value Facilities licence.
- Tabby+: a subscription at AED 49 a month after a free first month, with 1% cashback, priority support and other perks.
- Government fees: in the UAE, MOHRE lets you pay fees and fines of up to AED 20,000 through Tabby.
Tamara focuses more on shopping: exclusive deals, cashback at partner stores, a store finder, and the Smart and Smart+ subscriptions for extra benefits and shopping anywhere.
Winner: Tabby.
5. Availability: depends on your country
| Country | Tabby | Tamara |
|---|---|---|
| UAE | ✔ | ✔ |
| Saudi Arabia | ✔ | ✔ |
| Kuwait | ✔ | ✔ |
| Bahrain | — | ✔ (licensed by the Central Bank of Bahrain) |
Both cover the three big markets. Tabby generally has the wider store network, but the store matters more than the app: big retailers usually accept both, and some smaller stores offer only one.
Important for UAE expats: both now appear on your credit report
From July 2026, the Etihad Credit Bureau includes Tabby and Tamara accounts in UAE credit reports, for existing and new customers, including relevant historical data. Here's what that means:
- On-time payments help. If you're new to the country with little credit history, paying your plans on time can help you build a profile.
- Missed payments hurt your score and can show up when you apply for a loan, a credit card or a mortgage.
- Open plans count as commitments. Several plans across both apps add to the monthly obligations a bank sees under the 50% debt burden ratio limit. Before you apply for a loan, check your numbers with our DBR calculator.
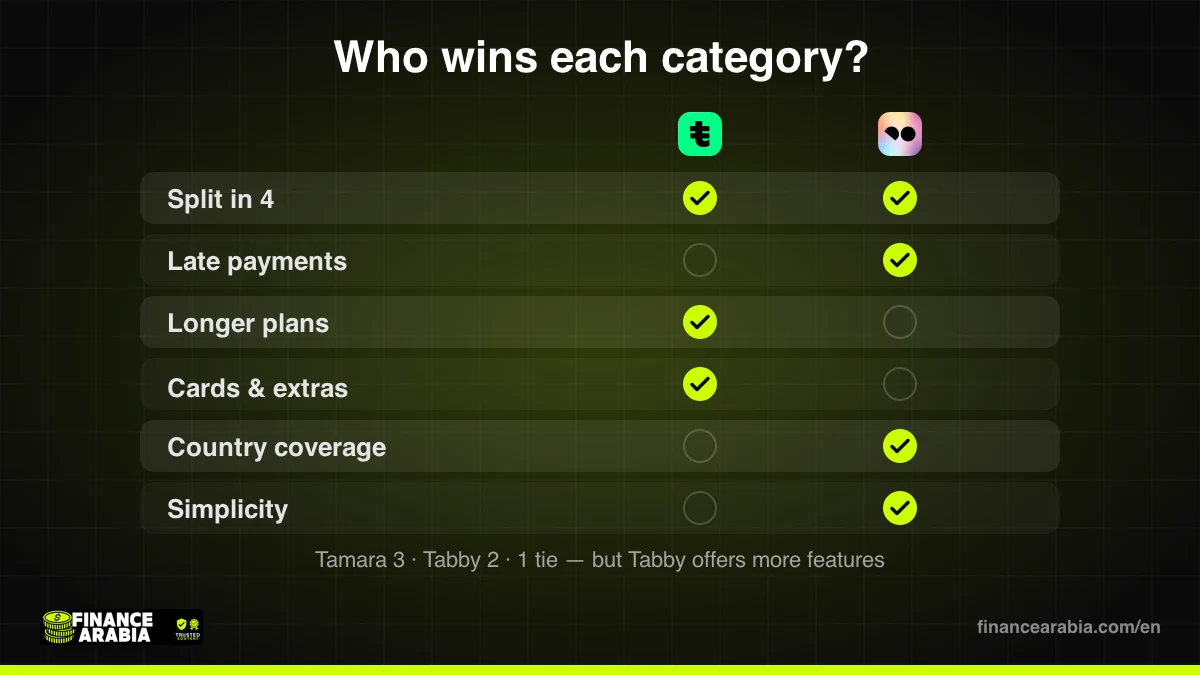
Final scorecard
| Category | Winner |
|---|---|
| Split in 4 | Tie |
| Late payments | Tamara |
| Longer plans | Tabby |
| Cards and extras | Tabby |
| Country coverage | Tamara (adds Bahrain) |
| Simplicity | Tamara |
Which should you choose?
- You want a card and a full money app: Tabby.
- You're worried about penalties if you forget a payment: Tamara.
- You live in Bahrain: Tamara.
- You're planning a large purchase over many months: Tabby has more options, but compare the total cost with cash or a bank loan first.
Golden rules for either app
- Use BNPL for things you'd buy anyway, not to afford things you can't.
- Keep track of everything you owe across both apps, not each one on its own.
- Don't open a new plan before the last one is finished if your instalments are piling up.
- Keep total monthly instalments at a comfortable share of your salary. Our budget planner can help.
Read our full reviews: Tabby review and Tamara review.
FAQs
Is Tabby or Tamara better in the UAE?
Tabby offers more features (Tabby Card, Tabby Cash and MOHRE payments), but it charges collection fees on missed payments in the UAE. Tamara says it charges no late fees. If you're disciplined about due dates, Tabby gives you more; if you're worried about forgetting, Tamara is more forgiving.
Can I use Tabby and Tamara at the same time?
Yes. Just remember that both appear on your UAE credit report and both count as commitments, so add up your instalments across the two apps.
Are Tabby and Tamara halal?
Both say their products are Sharia-compliant, and split-in-4 carries no interest. Longer plans involve a profit margin or fees, so check with the Sharia authority you follow if that matters to you.
Do Tabby and Tamara check my credit?
Both run eligibility and identity checks before approving purchases, and set a spending limit that changes with your repayment history.
Information from Tabby's and Tamara's official websites and public announcements, and from news reports, as of October 2026. Fees and terms change and differ by country; check the app for the terms where you live. This article is educational and is not financial advice.
Prices, fees and features change often. We check our facts at the time of writing, but always confirm the latest details with the provider. This article is for information only and is not financial advice.