Tabby Review: Split in 4 and 12-Month Plans — Is It Really Free?
"Split in 4" is at almost every checkout — but what does it really cost? A hands-on look at Tabby, its new longer plans and what to watch out for.
By the Finance Arabia team4 min read
Open almost any online store in Saudi Arabia or the UAE today and you'll see "Split in 4 with Tabby" under the checkout button. The pitch is tempting: take the product home today, pay a quarter of the price now and no interest. But is it really free? And what's the difference between split-in-4 and the longer instalment plans Tabby launched in 2026? Here's a practical review of what the app offers and what to watch out for.
Quick verdict
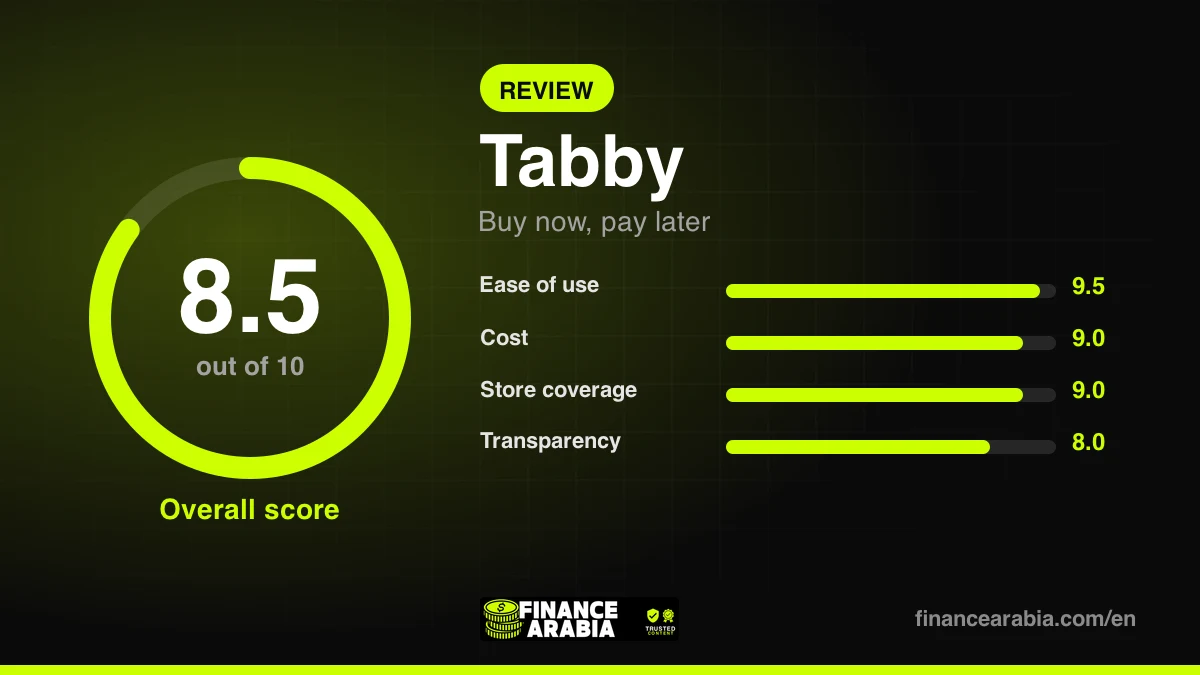
| Overall score | 8.5 / 10 |
|---|---|
| Best for | Spreading the cost of essential purchases |
| Biggest strength | Split in 4 with no interest or late fees |
| Biggest drawback | Can encourage impulse buying |
| Ease of use | 9.5 / 10 |
| Cost | 9.0 / 10 |
| Store coverage | 9.0 / 10 |
| Transparency | 8.0 / 10 |
What is Tabby?
Tabby is a fintech company founded in 2019 that offers buy now, pay later (BNPL) in Saudi Arabia, the UAE, Kuwait and other markets in the region. It works with thousands of online and in-store merchants — electronics, fashion, furniture, travel bookings and more. In 2026 it secured consumer-finance and SME-finance licences from the Saudi Central Bank, which significantly widened what it can offer.
Payment options
| Option | How it works | Interest | Best for |
|---|---|---|---|
| Split in 4 | A quarter at checkout, the rest in 3 monthly payments | None | Small and mid-sized purchases |
| Pay in full later | Pay the whole amount later, depending on the store's terms | None | Trying a product before paying |
| Longer instalments | Up to 12 monthly payments on purchases up to SAR 50,000 for eligible users | Sharia-compliant murabaha profit, no compounding late fees | Devices, furniture and big purchases |
The key point: split-in-4 genuinely is free in most cases, because Tabby earns a commission from the merchant, not from you. The longer instalment plans, on the other hand, are real financing with a profit margin — check the total amount before you accept and don't assume it costs nothing.
Late fees: what happens if you pay late?
In Saudi Arabia, Tabby scrapped late fees on split-in-4 in December 2023, and the longer plans use a murabaha structure without compounding late fees. That doesn't mean paying late has no consequences: the app may block new instalment purchases until you catch up, and your repayment behaviour can affect your credit record. Policies may differ in other countries — including the UAE — so check the terms for your country inside the app.
Using the app
- Tracking payments: all your purchases and upcoming due dates on one screen, with reminders before each payment.
- Early repayment: pay off any instalment early at no extra cost.
- Tabby Card: lets you split payments at stores that don't work with Tabby directly, within certain limits.
- Deals and cashback: the app shows exclusive discounts from partner stores, and the paid Tabby Plus membership adds extra perks for heavy users.
Pros and cons
| Pros | Cons |
|---|---|
| Split in 4 with no interest | Encourages impulse buying |
| No late fees on split-in-4 in Saudi Arabia | Longer plans carry a profit margin to watch |
| Instant approval at checkout | Your spending limit varies and isn't known in advance |
| Licensed by the Saudi Central Bank | Several small plans can quietly stretch your budget |
| Clear, simple app | Not every store offers the same options |
Tabby vs Tamara
| Feature | Tabby | Tamara |
|---|---|---|
| Core offer | Split in 4 and longer instalments | Pay in instalments and pay later |
| Coverage | Very wide in Saudi Arabia, the UAE and Kuwait | Wide, especially in Saudi Arabia |
| Sharia-compliant | Yes | Yes |
| Which to pick | Go with whichever the store supports and the better offer — the core service is very similar | |
How to use Tabby wisely
- Use it for needs, not wants: if you wouldn't buy it with cash, don't buy it in instalments.
- Add up your instalments: before any new purchase, check the total you'll owe over the next three months.
- Read the total cost on longer plans: compare it with the cash price or a bank financing offer.
- Turn on reminders: paying on time protects your limit and raises it over time.
FAQs
Is Tabby halal?
Split-in-4 has no interest, and the longer plans are based on murabaha and approved by a Sharia board, according to the company. For peace of mind, check with the Sharia authority you follow.
Does Tabby affect my credit score?
Since Tabby obtained finance licences, paying on time — or late — can show up in your credit assessment, so stick to your payment dates.
What's the maximum I can spend with Tabby?
Every user's limit is different and depends on repayment history; it rises gradually if you pay on time. Longer instalments go up to SAR 50,000 for eligible users.
The verdict
Tabby is a genuinely useful tool when you use it to spread a payment you'd make anyway — and a risky one when it becomes a way to buy things you don't need. Split-in-4 is one of the best free options for shoppers in the Gulf. Treat the longer plans like any other financing: work out the cost and compare before you tap "Confirm".
Information is correct as of October 2026; terms and fees can change. Check the official app for the terms that apply in your country.
Prices, fees and features change often. We check our facts at the time of writing, but always confirm the latest details with the provider. This article is for information only and is not financial advice.