Dubai Mortgage Upfront Costs: How Much Cash Do You Need Beyond the Down Payment?
A 20% deposit is only part of your buying budget. Calculate cash to complete, separate official charges from assumptions and stress-test a lower bank valuation.
By the Finance Arabia editorial team7 min read
A 20% down payment is only one part of the cash needed to buy a home in Dubai. Transfer and mortgage registration charges, agreed brokerage, bank costs and the gap between purchase price and valuation can all sit outside the number you first calculated. An affordable instalment does not automatically mean an affordable completion.
This guide builds a transparent budget for a hypothetical AED 1.5 million completed apartment, purchased by an expatriate for their own first home with an 80% loan assumption. It distinguishes official charges from negotiable or assumed costs, and shows what happens if the valuation is lower. It is not a bank offer or a quotation for a particular transaction.
What does an 80% mortgage actually mean?
The CBUAE mortgage regulations distinguish first owner-occupied homes from investment and subsequent properties. They provide an 80% maximum loan-to-value ratio for an expatriate's first owner-occupied home below AED 5 million. Different categories have different limits; banks can apply stricter credit criteria. A regulatory maximum is not a promise of approval.
For this AED 1.5 million example, 80% means AED 1.2 million borrowed and AED 300,000 paid from the buyer's own funds toward the price. Do not treat this owner-occupier example as a rule for a second property, an investment purchase, an off-plan unit or a non-resident application. Ask the bank to confirm your classification and valuation basis in writing.
Separate official registration charges from your commercial agreement
| Item | Official rule or budget treatment | What to ask |
|---|---|---|
| Sale registration | DLD service page lists 2% seller and 2% buyer | Who pays each share under the signed agreement? |
| Mortgage registration | DLD lists 0.25% of mortgage value | What issuance and channel charges also apply? |
| Sale registration service partner | DLD lists AED 4,000 plus VAT for sales of AED 500,000 or more | Is this included or separately quoted? |
| Title, map and other applicable charges | Additional items depend on service and property | Can the trustee itemise the actual transaction? |
| Brokerage, bank and valuation | Use written provider quotations | Is VAT included, and when is each amount due? |
The service details are on DLD's Property Sale Registration and Mortgage Registration pages. Do not add every charge from every channel indiscriminately: ask the bank and trustee which services will actually be used and whether any amount is already included in a combined quotation.
A budget showing 4% of the price payable by the buyer needs an explicit assumption: the buyer has agreed to bear both sale-registration shares. The official service page itself lists the two shares separately. Likewise, a 2% brokerage fee or a 1% bank fee in a sample budget is an assumption, not a universal government tariff.
Worked example: the cash needed for an AED 1.5 million home
Assume the bank finances AED 1.2 million. The buyer agrees to pay both registration shares. Assume a broker quotation of 2% plus 5% VAT on that fee, a bank processing quotation of 1% of the loan plus 5% VAT on that fee, and the additional allowances below. Replace all assumptions with your own written figures.
| Budget line | Basis | Cash amount |
|---|---|---|
| Equity toward purchase price | 20% × 1,500,000 | 300,000 |
| Both sale-registration shares, assumed buyer-paid | 4% × 1,500,000 | 60,000 |
| Brokerage, assumed quotation including VAT | 2% × 1,500,000 × 1.05 | 31,500 |
| Bank processing, assumed quotation including VAT | 1% × 1,200,000 × 1.05 | 12,600 |
| Mortgage percentage registration charge | 0.25% × 1,200,000 | 3,000 |
| Sale service-partner fee including assumed 5% VAT | 4,000 × 1.05 | 4,200 |
| Valuation allowance | Assumed all-in quote | 3,150 |
| Other applicable issuance/channel charges | Planning allowance; verify itemisation | 5,000 |
| Subtotal before moving and reserves | Sum of above | 419,450 |
| Moving and initial setup allowance | Assumed | 10,000 |
| Cash needed under these assumptions | Subtotal + setup | 429,450 |
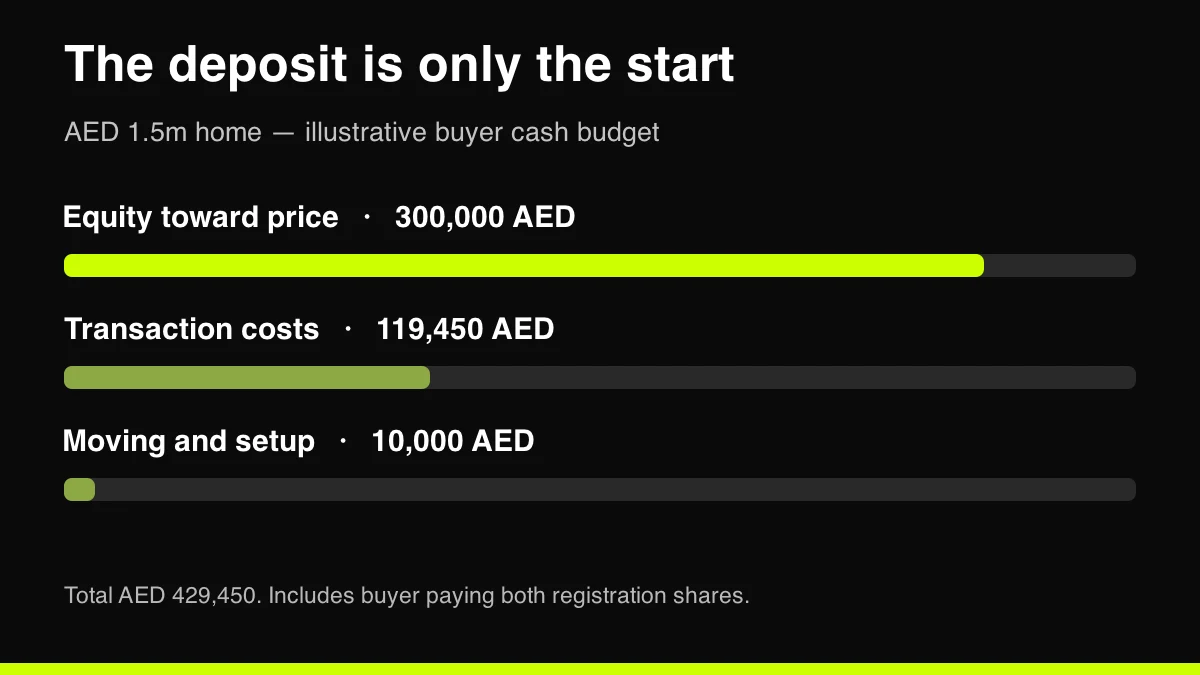
The result is about 28.63% of the purchase price, before a separate emergency reserve, service-charge adjustments, insurance and any other property-specific costs. It is not a market-wide “minimum percentage”. If the seller pays their own 2% registration share, this example falls by AED 30,000. If your bank or broker quote changes, the total changes again.
Also distinguish cash timing from total cash needed. A contractual booking or sale deposit that is credited toward the purchase price is part of your equity, not a second down payment. Record when it becomes payable and whether it is refundable under your agreement. Never assume the refund treatment without checking the signed terms.
What if the bank values the property below your offer?
Suppose your agreed price remains AED 1.5 million, but the bank confirms it will lend 80% of an AED 1.4 million valuation. The loan becomes AED 1.12 million rather than AED 1.2 million. You now need AED 380,000 toward the price, an extra AED 80,000.
| Bank valuation | Loan | Buyer equity toward AED 1.5m price |
|---|---|---|
| AED 1,500,000 | AED 1,200,000 | AED 300,000 |
| AED 1,450,000 | AED 1,160,000 | AED 340,000 |
| AED 1,400,000 | AED 1,120,000 | AED 380,000 |
Some loan-linked fees would be slightly lower with a smaller loan, but that does not remove the equity gap. Using the budget assumptions above, the AED 1.12 million loan reduces the assumed processing fee by AED 840 and the percentage mortgage registration charge by AED 200. The revised total becomes AED 508,410, with other assumptions unchanged.
Before paying a non-refundable amount, ask how a low valuation or failed final approval is handled. A mortgage pre-approval is not a substitute for the lender's final property-specific conditions or the financing clause in your purchase agreement.
Stress-test the monthly instalment as well
For a hypothetical AED 1.2 million amortising loan over 25 years, the table below assumes monthly payments, a constant nominal annual interest rate divided by twelve and no fees inside the payment. It is a mathematical illustration, not a current rate offer or an APR comparison.
| Constant annual rate assumption | Approximate monthly payment | Difference versus 4% |
|---|---|---|
| 4% | AED 6,334 | — |
| 5% | AED 7,015 | AED 681 |
| 6% | AED 7,732 | AED 1,398 |
The calculation uses payment = principal × r ÷ [1 − (1 + r)−n], with r the monthly rate and n = 300. An actual fixed-period or variable-rate loan can reset, and takaful or insurance, fees and other costs may be separate. Check the reference rate, margin, reset frequency and what happens after the introductory period.
Budget recurring ownership costs too: service charges, maintenance, insurance, utilities and any financing-linked cover. Compare those with rent before describing the entire instalment as the cost of ownership. Part of an amortising payment reduces your principal; fees and interest do not.
Seven checks before you commit
- Get your borrower category, lending ceiling and valuation basis in writing.
- Ask for a dated cash-to-complete statement from the bank and trustee.
- Confirm how sale-registration fees are shared in the contract.
- Mark all quoted amounts as VAT-inclusive or VAT-exclusive.
- Record deposit timing, credit toward price and refund conditions.
- Test a lower valuation and higher payment against your actual savings and income.
- Keep an emergency reserve outside completion cash, including known upcoming obligations.
Frequently asked questions
Can I buy with exactly 20% saved?
That only covers equity in the particular 80% lending example. You still need to account for transaction costs, setup, valuation risk and reserves. Your actual loan approval may also be lower.
Is brokerage always 2%?
No fixed brokerage rate is asserted here. Two percent is a sample commercial quotation. Read the agreed amount, VAT treatment and payment trigger in your own contract.
Can transaction costs be financed?
Do not build your budget around that assumption. Ask your lender to state what it funds and what must come from your own cash under the current applicable rules. This example treats the listed costs as buyer cash.
Should I compare buying with renting?
Yes. Compare the expected time in the home, purchase and eventual sale costs, maintenance, financing and the cash tied up. For a practical renewal alternative, read our Dubai rent-increase guide. A short expected stay can change the result materially.
Sources and calculation notes
Reviewed 17 October 2026: CBUAE mortgage regulations, DLD sale registration and DLD mortgage registration. Budgets, valuation scenarios and amortisation examples were calculated by the editorial team using stated assumptions. Images are illustrative. For loan-readiness context, see our AECB credit score guide. This is educational budgeting guidance, not individual lending or legal advice.
Run the numbers yourself
Prices, fees and features change often. We check our facts at the time of writing, but always confirm the latest details with the provider. This article is for information only and is not financial advice.