How to Protect Your Money From Inflation: A Practical Guide
Inflation quietly shrinks money left in the bank — and savings back home can shrink even faster. Practical steps to protect your purchasing power.
By the Finance Arabia editorial team3 min read
Prices keep rising, while the money sitting in your bank account quietly buys a little less every year. That's inflation — and if you're saving in a Gulf currency while supporting family in a country with higher inflation, it can hit you twice. Here's what inflation actually does to your money and the practical steps that protect it.
What inflation really costs you
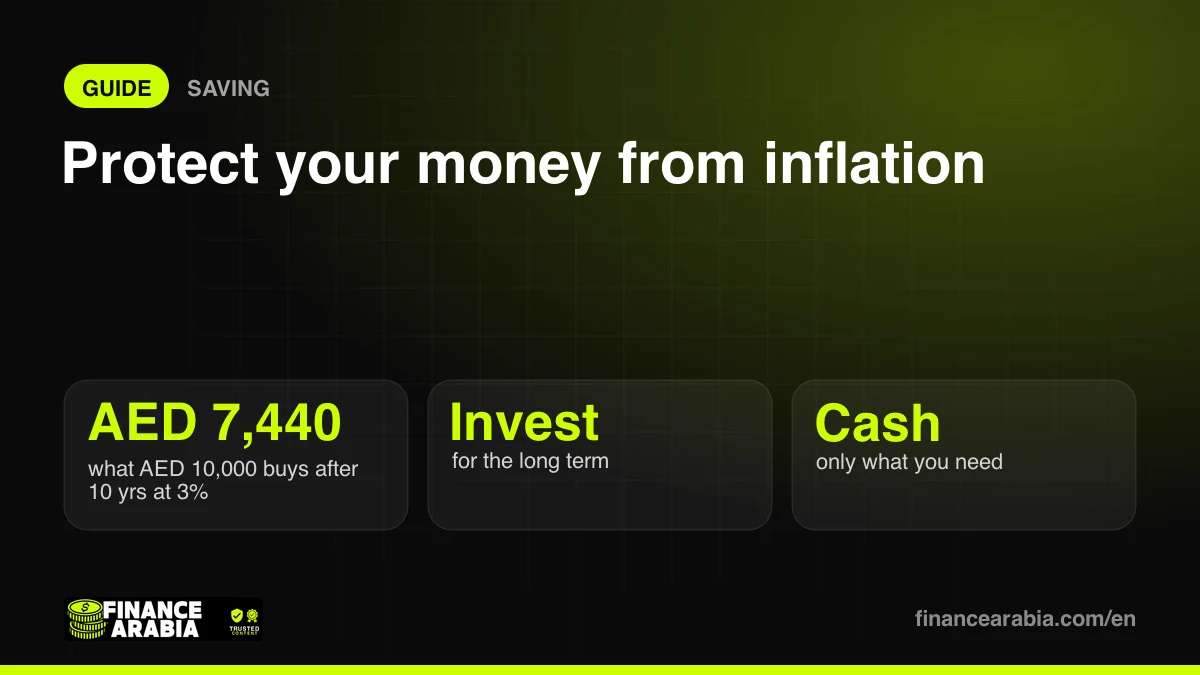
Inflation is the rate at which prices rise — or, put the other way, the rate at which your money loses purchasing power. At 3% a year, AED 10,000 of savings buys only about AED 7,400 worth of today's goods after ten years. At 10% a year, a rate many home countries have seen, the same money is worth less than half within eight years.
Try your own numbers in our inflation calculator.
Why it happens
- Rising global energy and food prices
- Higher production and shipping costs
- Strong demand meeting limited supply
- Rapid money creation or currency weakness in some economies
- Economic shocks and conflicts
You can't control any of these. You can control what your money does while they happen.
1. Invest for the long term
Cash in a current account loses value every year. Long-term investments give your money a chance to grow faster than prices.
- Broad stock index funds (ETFs): global or US indices such as the MSCI World or S&P 500 have historically beaten inflation over long periods, though they fall sharply at times.
- Real estate and REITs: property values and rents tend to rise with prices over time; REITs let you invest without buying a whole property.
- Gold: often holds its value when currencies weaken. Many investors keep a modest slice — commonly somewhere around 5–10% — as a hedge rather than a growth engine. Check today's price on our gold page.
See how regular investing can compound over time with the compound interest calculator.
2. Grow your income
The most powerful inflation hedge is earning more. Ask for regular salary reviews, build skills that raise your market value, or add a side income. A 10% pay rise does more for you than any clever investment trick.
3. Keep only the right amount in cash
You do need cash — for an emergency fund of 3–6 months of expenses and for goals in the next year or two. Beyond that, large cash balances simply shrink in real terms.
4. Clear expensive debt
Credit card interest of 30%+ a year is far higher than any inflation rate. Paying it off is a guaranteed "return" that beats almost any investment.
5. Watch out for inflation back home
If you're saving in, or sending money to, a country with high inflation — such as Egypt, Pakistan or Lebanon in recent years — savings held in that currency can lose value quickly. Many expats keep long-term savings in their Gulf currency or in globally diversified investments, and send money home when it's actually needed. Compare rates with our currency converter.
6. Spend smarter, not less
- Cancel subscriptions you don't use.
- Buy staples in bulk and compare supermarket prices.
- Time big purchases for major sales seasons.
- Avoid buying things early "before prices rise" unless you genuinely need them.
A simple action plan
| When | Action |
|---|---|
| Today | Work out your monthly essentials and current cash balance |
| This week | Set up an automatic monthly transfer to savings or investments |
| This month | Complete or top up your emergency fund; list debts by interest rate |
| This year | Invest surplus cash for the long term; review your salary and skills |
The bottom line
You can't stop inflation, but you can stop it from eating your savings: keep a sensible cash buffer, invest the rest for the long term, clear expensive debt and keep growing your income.
This article is for general information only and is not investment advice. Investments can fall as well as rise.
Prices, fees and features change often. We check our facts at the time of writing, but always confirm the latest details with the provider. This article is for information only and is not financial advice.