How Much Personal Loan Can I Get in the UAE? DBR, 20× Salary and the 48-Month Rule
Three Central Bank rules decide your maximum personal loan — and your credit cards quietly shrink it. A worked example, the flat-rate trap and the fees to budget for.
By the Finance Arabia team4 min read
"How much can I borrow on my salary?" is one of the most common money questions in the UAE — and the answer isn't just up to your bank. The Central Bank of the UAE (CBUAE) sets hard limits on personal loans, and banks apply them on top of their own credit checks. This guide explains the three rules that decide your maximum loan, shows a worked example and covers the costs people often miss. To run your own numbers, use our DBR calculator and loan EMI calculator.
The three rules that cap your loan
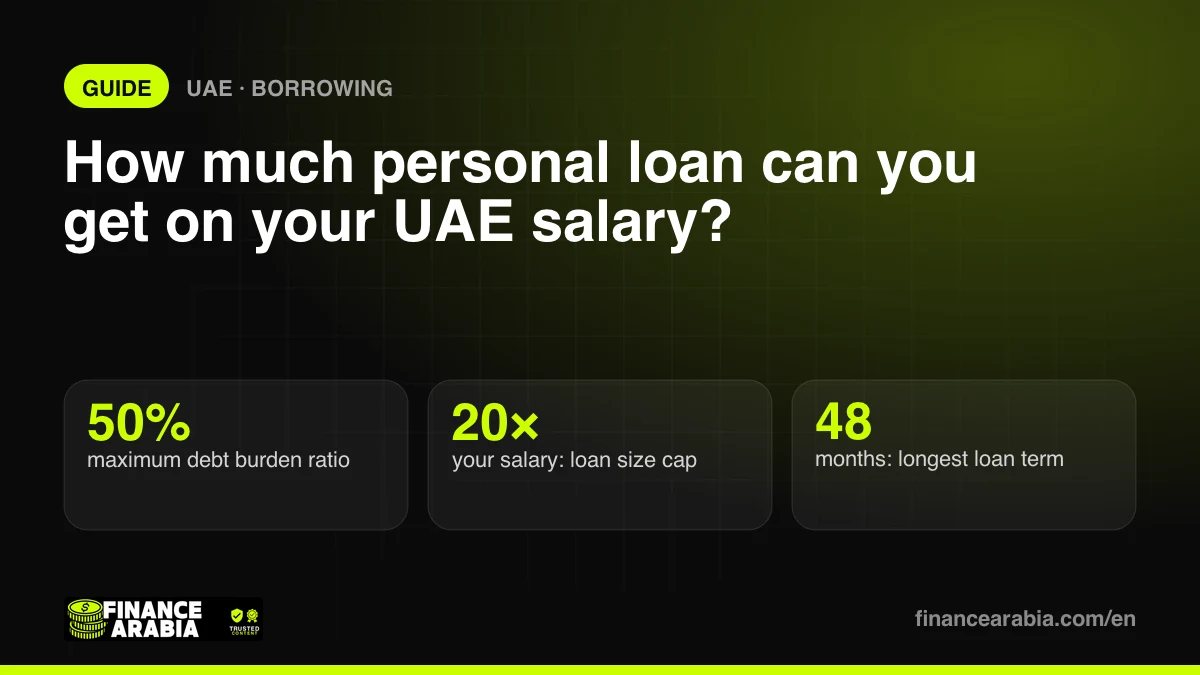
Under CBUAE Regulation No. 29/2011 on bank loans to individuals, a personal loan must stay within all three limits below — whichever is lowest wins:
| Rule | Limit | Example on AED 15,000 salary |
|---|---|---|
| Debt burden ratio (DBR) | All monthly debt repayments ≤ 50% of gross salary | Max AED 7,500/month in total repayments |
| Loan size | ≤ 20 times your monthly salary | Max AED 300,000 |
| Term | ≤ 48 months for personal loans | 4 years maximum |
What counts towards your DBR?
Everything you already owe each month: existing personal and car loan instalments, mortgage payments, and your credit cards. Banks usually count a percentage of your total card limit — not your actual spending — as a monthly obligation, so a card you never use can still reduce what you can borrow. Closing unused cards before applying can make a real difference.
Worked example
Ahmed earns AED 15,000 a month and has credit cards that the bank counts as AED 1,000 a month. He wants a 48-month loan at 6% a year (reducing rate).
- DBR room: 50% × 15,000 = AED 7,500. Minus existing obligations of AED 1,000 = AED 6,500 maximum new instalment.
- What AED 6,500 a month can repay: over 48 months at 6%, that's roughly AED 276,800.
- 20× salary cap: 20 × 15,000 = AED 300,000.
- Result: the lower figure applies, so Ahmed's maximum is about AED 276,800 — before the bank's own credit assessment.
Try the same calculation with your figures in the DBR calculator.
Flat rate vs reducing rate: the most expensive misunderstanding
Many UAE loan adverts quote a flat rate. Interest is charged on the full original amount for the whole term, even as you pay it down. A reducing rate charges interest only on what you still owe. The same number means very different costs:
| AED 100,000 over 4 years | 3.5% flat | 3.5% reducing |
|---|---|---|
| Monthly instalment | AED 2,375 | AED 2,236 |
| Total interest | AED 14,000 | AED 7,310 |
| Equivalent APR | About 6.6% | 3.5% |
Always ask the bank for the reducing (APR) rate and compare offers on that. Our loan calculator converts a flat rate into its real APR.
Fees to budget for
- Processing fee: often a percentage of the loan, sometimes waived in promotions.
- Life insurance: commonly required and added monthly.
- Early settlement fee: capped by the Central Bank at 1% of the outstanding amount or AED 10,000, whichever is lower — for full or partial settlement.
- Late payment charges if you miss an instalment.
How to improve your chances (and your rate)
- Check your AECB credit report and score before applying — you can request it from the Al Etihad Credit Bureau.
- Apply with the bank that receives your salary. Salary-transfer loans usually come with better rates.
- Reduce card limits you don't need, to free up DBR.
- Borrow only what you need — a smaller loan over a shorter term costs far less in total.
- Compare at least three offers on APR, fees and insurance, not on the headline rate.
FAQs
What is the minimum salary for a personal loan in the UAE?
It depends on the bank. Many set minimums around AED 5,000 a month, and some require more for non-salary-transfer loans.
Can I get a personal loan longer than 4 years?
Not for a standard personal loan — the Central Bank caps it at 48 months. Mortgages and some car loans follow different rules.
Does a buy-now-pay-later plan count in my DBR?
BNPL providers increasingly report to credit bureaus, and banks may take regular instalments into account. Treat them as debt when you plan.
The bottom line
Your maximum UAE personal loan is the lowest of three limits: 50% DBR, 20× salary and a 48-month term. Your existing cards and loans eat into the first one, and a flat rate can hide nearly double the interest. Run your numbers in the DBR calculator before you walk into a bank.
Based on CBUAE Regulation No. 29/2011 and its amendments as of October 2026. Banks apply their own credit policies on top of these limits. This guide is general information, not financial advice.
Prices, fees and features change often. We check our facts at the time of writing, but always confirm the latest details with the provider. This article is for information only and is not financial advice.